

How buyers are keeping low VA rates in Colorado Springs
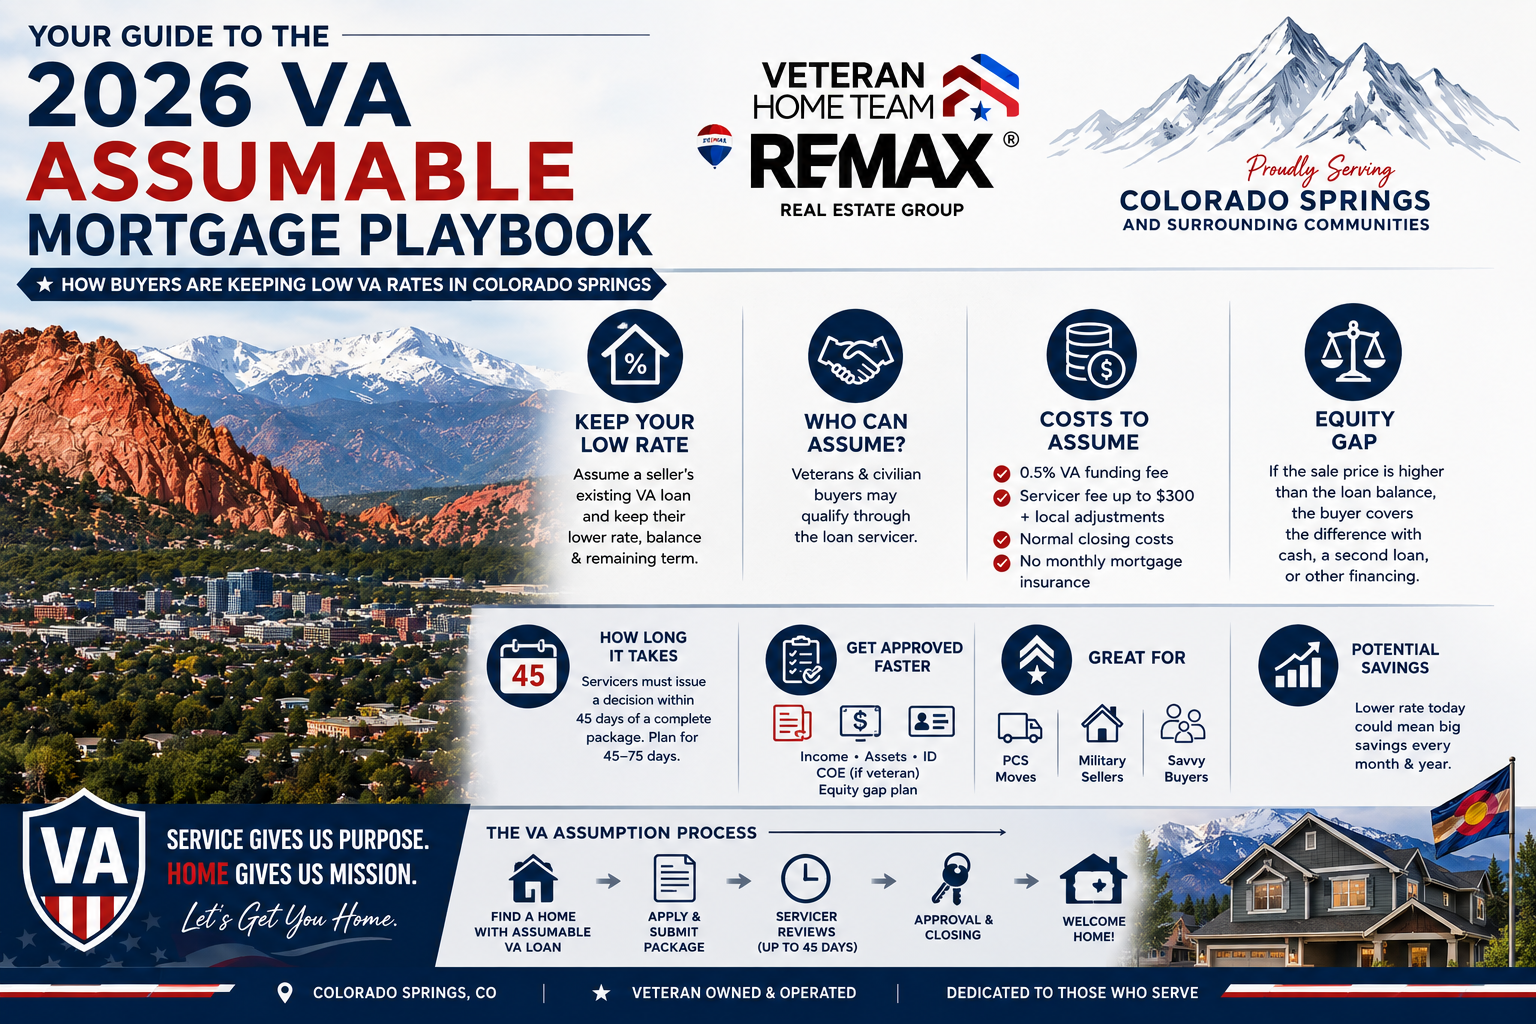
Infographics for How buyers are keeping low VA rates in Colorado Springs.
Why VA assumable loans matter right now:
If you are buying a home in Colorado Springs in 2026, you may not have to settle for a brand-new mortgage rate. Some homes have existing VA loans with rates significantly below today’s market. Instead of replacing that loan, a qualified buyer may be able to assume the seller’s loan and keep the existing rate, balance, and remaining term. With new mortgage rates considerably higher than the rates many military families secured in 2020 and 2021, the potential monthly savings can be significant.
How a VA assumption works:
VA loans are assumable. A buyer must qualify through the current loan servicer, similar to applying for a new mortgage. The process can include credit, income, employment, debt, and residual income review. Both veterans and civilian buyers can potentially assume a VA loan. If you are a veteran, you may also be able to substitute your VA entitlement so the seller can have their entitlement restored. For military sellers preparing for a PCS, that can be a major benefit.
What it costs:
A VA loan assumption can involve a 0.5% VA funding fee, a servicer processing fee of up to $300 plus applicable local adjustments, and normal closing costs. VA loans do not require monthly mortgage insurance. The equity gap explained: This is the part buyers need to understand before getting excited about the low rate. If the purchase price is higher than the existing loan balance, the buyer must cover the difference. For example, if a Colorado Springs home sells for $500,000 and the assumable VA loan balance is $300,000 at 3%, the buyer needs to cover the remaining $200,000. That gap could potentially be covered with cash, a second loan, or other approved financing. Even when additional financing is needed, the overall blended payment may still be lower than financing the entire purchase with a new mortgage at today’s rates.
How long it takes and the 45-day rule:
VA Circular 26-23-27 requires servicers with automatic authority to issue a decision within 45 calendar days after receiving a complete assumption package. Servicers without automatic authority must forward the complete package to VA within 35 calendar days. Buyers should plan for approximately 45 to 75 days for the overall process, with longer timelines possible when documentation is incomplete.
What to bring to get approved quickly:
Be prepared with two years of W-2s or tax returns, your most recent LES or pay stubs, recent bank statements showing funds available for the equity gap and closing costs, photo ID, and, if you are a veteran, your Certificate of Eligibility. It can also help to provide a letter explaining how you plan to cover the equity gap. A complete package from the beginning can help keep the process moving.
Who should consider a VA assumption:
If you are PCSing to Colorado Springs and have VA entitlement available for substitution, an assumable loan could be an excellent opportunity. If you are a seller with a low-rate VA loan, marketing that assumable feature can help your home stand out to buyers. Civilian buyers can also potentially assume VA loans, although they cannot substitute VA entitlement for the seller.
Want to see your exact savings on this home?
Text or email me the property address and your estimated cash available for closing. I can help you compare the assumed payment and equity gap against a new loan so you can see the potential monthly and yearly savings before you write an offer.
Julie Robertson | Colorado Springs VA Realtor
USAF Retired | Realtor® | ABR | MRP
VA Assumable & PCS Specialist
(719) 367-8676
Veteran Home Team | RE/MAX Real Estate Group

